 Article Editor
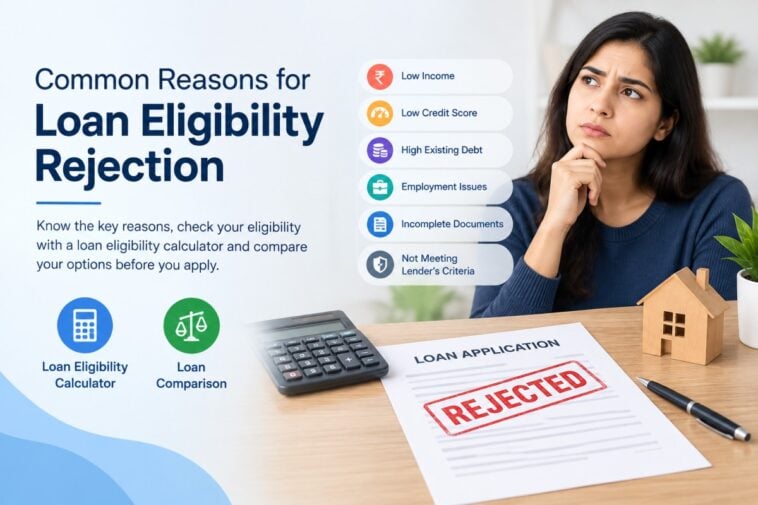
Applying for a loan does not always guarantee approval. Lenders check several factors before deciding whether an applicant qualifies for a loan. These factors may include income, credit history, existing debts, employment stability, repayment capacity, and other eligibility requirements.
Understanding the common reasons for loan eligibility rejection can help borrowers prepare better before submitting an application. Using a loan eligibility calculator and completing a loan comparison can also help you understand your borrowing capacity and choose suitable loan options.
1. Low or Unstable Income
Income is one of the key factors lenders consider when assessing loan eligibility. If your income is too low compared with the requested loan amount, the lender may consider the repayment burden too high.
Applicants with irregular or unstable income may also face difficulties, particularly when the lender requires consistent proof of earnings. Before applying, use a loan eligibility calculator to estimate a reasonable loan amount based on your income and repayment capacity.
2. Low Credit Score
Your credit history gives lenders an idea of how you have managed previous borrowing. Missed payments, defaults, high outstanding balances, or frequent credit applications may negatively affect your credit profile.
A weaker credit history can make it harder to meet certain loan eligibility requirements or may result in less favorable loan terms. Checking your credit report and correcting errors, if any, can be useful before applying for new credit.
3. High Existing Debt
Existing loans and credit card balances can reduce your ability to take on additional debt. Lenders generally consider your current monthly obligations when evaluating repayment capacity. For example, if a large portion of your monthly income is already committed to EMIs, a new loan may increase your overall financial burden.
A loan eligibility calculator can help you understand how your existing obligations may affect the amount you could potentially borrow.
4. Applying for a Loan Amount That Is Too High
Requesting a loan that is significantly higher than your repayment capacity can lead to rejection. Instead of choosing an amount based only on your financial needs, consider your monthly income, existing EMIs, regular expenses, and expected repayment period.
Estimating your affordable EMI before applying can help you select a more realistic loan amount.
5. Short Employment History or Irregular Employment
Employment stability can also influence loan eligibility. Some lenders may have minimum requirements related to employment duration, work experience, or business continuity. Frequent job changes or a short employment history may affect how a lender evaluates income stability.
Applicants should review the lender’s eligibility criteria before submitting an application.
6. Errors or Incomplete Information in the Application
Incorrect personal information, income details, employment information, or documentation can create problems during the application process.
Even a small mismatch between the application and supporting documents may require additional verification or delay the process.
Always review your application carefully and provide accurate information.
7. Too Many Recent Loan Applications
Submitting multiple loan applications within a short period may affect your credit profile because lenders may make credit inquiries during the assessment process.
Rather than applying to several lenders without checking their requirements, research available options first. A loan comparison can help you review factors such as interest rates, loan amounts, tenure, fees, and eligibility conditions before deciding where to apply.
8. Not Meeting the Lender’s Specific Criteria
Every lender can have its own eligibility requirements. These may include minimum income, age, employment type, credit history, location, loan amount, or repayment period. Meeting one lender’s requirements does not necessarily mean you will meet another lender’s criteria. Therefore, always check the specific eligibility conditions before submitting an application.
How a Loan Eligibility Calculator Can Help
A loan eligibility calculator provides an estimate of the loan amount you may qualify for based on information such as income, existing obligations, interest rate, and repayment tenure. It can help you:
- Estimate potential borrowing capacity
- Understand possible EMI commitments
- Plan a suitable loan amount
- Review affordability before applying
- Reduce unnecessary loan applications
The result from a calculator is an estimate and does not guarantee loan approval. The final decision depends on the lender’s assessment and applicable eligibility criteria.
Why Loan Comparison Matters Before Applying
Loan comparison can help you understand the differences between available borrowing options. Instead of focusing only on the advertised interest rate, consider the overall cost of borrowing.
Compare factors such as:
- Interest rate
- Processing fees
- Loan tenure
- Estimated EMI
- Prepayment or foreclosure conditions
- Eligibility requirements
- Other applicable charges
Combining loan comparison with a loan eligibility check can help you make a more informed borrowing decision.
How to Improve Your Loan Eligibility
If your application is rejected, review the possible reasons before applying again. You may consider reducing existing debt, improving repayment history, choosing a more affordable loan amount, maintaining stable income, or correcting inaccurate information in your credit report.
Using a loan eligibility calculator before reapplying can also help you set a realistic borrowing amount.
Conclusion
Loan eligibility rejection can happen for several reasons, including low income, weak credit history, high existing debt, unstable employment, excessive loan applications, or failure to meet specific lender requirements.
Before applying, understand your financial position, use a loan eligibility calculator to estimate your borrowing capacity, and conduct a loan comparison to review suitable options. Careful preparation can help you approach the loan application process with a clearer understanding of your potential eligibility and repayment capacity.